
Using Hard Money Loans for Rental Property Upgrades
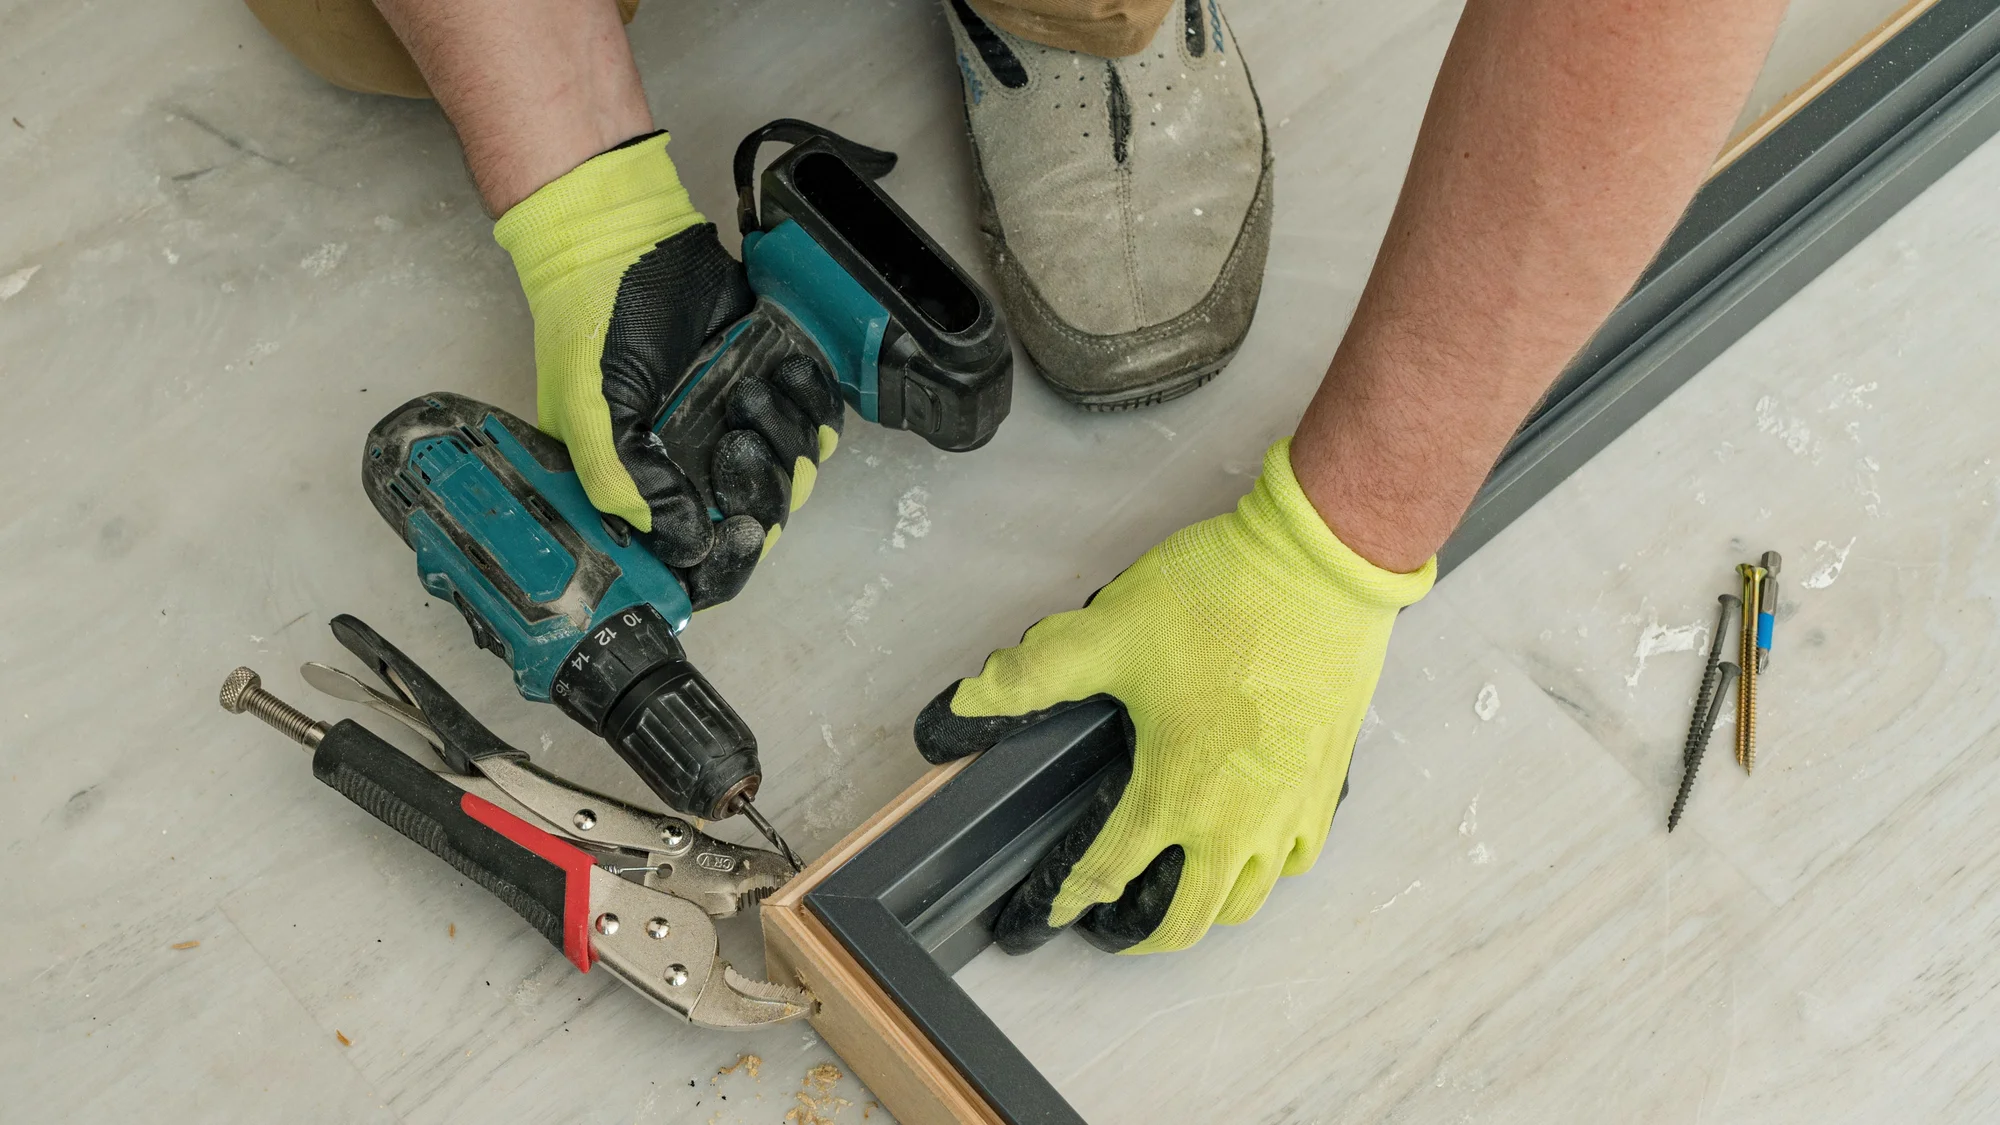
Renovating rental properties is one of the most reliable ways to increase both property value and monthly cash flow. But traditional bank financing moves slowly, and many properties that need renovation do not qualify for conventional loans in their current condition. Hard money loans solve both problems by providing fast funding based on the property's potential rather than its current state.
What Is a Hard Money Loan?
A hard money loan is financing from a private lender or company like Veristone. These loans are secured by the property itself and focus on the asset's value and project potential rather than the borrower's credit score. They fund faster than bank loans and offer more flexibility on terms, making them well-suited for renovation projects.
Why Hard Money Works for Rental Renovations
Three advantages make hard money ideal for rental property upgrades. First, speed: you can close in days rather than weeks, which matters in competitive markets. Second, flexibility: lenders can structure terms around your specific project. Third, access: hard money lets you purchase properties that banks would reject due to their current condition.
Choose the Right Renovation Projects
Not every upgrade produces the same return. Focus on improvements that increase rental income and property value. Kitchen and bathroom updates, energy-efficient systems, additional bedrooms, and improved curb appeal consistently deliver the best ROI for rental properties. Avoid cosmetic-only improvements that look nice but do not move the rent needle.
Understand the Loan Terms
Hard money loans carry higher interest rates and shorter terms than conventional mortgages. Know your total borrowing costs before you start. Factor in interest rates, origination points, fees, and the loan term. The numbers need to work even in a scenario where the renovation takes longer or costs more than planned.
Managing the Renovation with Draw Schedules
Most hard money renovation loans disburse funds in stages based on project milestones. This draw schedule keeps the project moving forward while giving the lender visibility into progress. Since lenders focus on the after-repair value, they are often willing to finance most or all of the renovation costs when the value increase supports it.
Real-World Example
Consider an investor who purchases a neglected fourplex using a hard money loan. By targeting high-impact renovations like updated kitchens, modern fixtures, and improved common areas, the investor increases rental income by 50%. After renovation, they refinance into a conventional loan at a much lower rate. The hard money loan was expensive for those few months, but it enabled a deal that now produces strong ongoing returns.
Managing Risk on Rental Renovations
The main risks are renovation delays, cost overruns, and market shifts. Protect yourself with a detailed renovation plan, a contingency budget of at least 10-15% above your estimate, and a clear understanding of the local rental market. Make sure you can carry the property costs if it takes longer than expected to rent or refinance.
Refinancing After Renovation
The typical exit strategy for a hard money rental renovation loan is refinancing into a long-term conventional mortgage. Once the property is renovated and appraised at its higher value, you qualify for a lower-rate mortgage based on improved cash flow and property condition. This is where the real profit locks in.
Selecting the Right Hard Money Lender
Choose a lender with experience in rental property financing, transparent terms, and a solid reputation. Veristone, for example, offers expertise in structuring renovation loans and acts as a partner throughout the project, not just a source of capital.
Hard money loans for rental renovations are a proven strategy for building equity and cash flow quickly. The key is choosing the right projects, managing costs tightly, and having a clear plan for refinancing once the work is done. With the right lender and a disciplined approach, you can transform underperforming rentals into strong-performing assets.